 Brazil

 Kenya

 Philippines

 Mexico

 Saudi Arabia


Challenge & Solution
Most cross-border providers process from abroad, applying the same acquiring logic to São Paulo, Lagos, and Jakarta that they use in New York or London.
dLocal Payins combines local acquiring, local payment methods, and approval rate optimization built for the markets where cross-border providers lose revenue to declines.
-
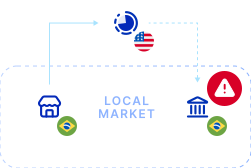 Cross-border providers
Challenge: Cross-border acquiring
When transactions are processed from outside the market, approval rates drop, fraud flags rise, and soft declines increase compared to what local rails deliver.
Revenue lost at every decline
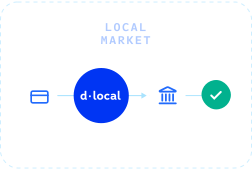 dLocal Payins
Solution: Local acquiring
Each transaction runs through a network of local acquirers and is routed to the rail most likely to approve it, so more of your customers complete checkout.
More revenue captured at checkout
-
 Cross-border providers
Challenge: Limited payment method coverage
Each market runs on its own mix of local payment methods, and customers who can’t find the one they trust at checkout leave before they pay.
Lost sales before payment even starts
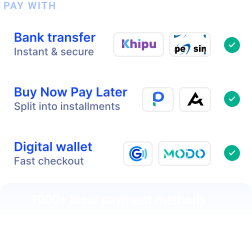 dLocal Payins
Solution: Local payment methods
One integration gives you access to 1000+ payment methods across 60+ emerging markets, with the right mix shown per country.
More customers pay with the payment method they trust
-
 Cross-border providers
Challenge: Country-by-country setup
Expanding into each market means new licenses, bank accounts, and approvals to repatriate funds before you process a single payment.
Expansion slowed by every new market
 dLocal Payins
Solution: Local infrastructure
Local licenses and FX access are already in place in each market, so you start accepting payments without building local infrastructure yourself.
New markets, ready to sell in, without the setup
Proven performance
up to +24pp conversion rate*
with local acquiring vs. cross-border acquiring
*Results may vary by industry, method, and market
60+ Emerging Markets
1000+ Local payment methods
1 Integration
“In Latin America, and in every market we operate, the payment experience needs to feel local, not imported. Working with dLocal helps us reduce friction at checkout and better support how our users want to pay.”
Local payment methods bring in new customers.
dLocal’s expertise turns them into revenue.
-
Local cards
Debit and credit cards issued by local banks.
Local cards
Card is still how most buyers pay in emerging markets, but processed from abroad, approval drops. The rail that works everywhere fails quietly when it isn't local.
We connect directly to local acquirers and issuers in each market, with network tokens and 3DS calibrated per country to raise approval on every card transaction.
-
Real-time payments
Instant account-to-account payments.
Real-time payments
Instant payment rails like Pix in Brazil and UPI in India now move more volume than cards. Buyers expect immediate confirmation, not multi-day clearing.
Grow with real-time paymentsWe layer bank visibility, one-click flows, and pre-verification on top of native rails like Pix and UPI to raise checkout completion.
-
Buy Now, Pay Later
Installment payments with instant credit approval.
Buy Now, Pay Later
Most buyers in emerging markets don't hold a credit card. Local BNPL reaches them where cards can't.
Grow with BNPLWe connect your business to leading 10+ local BNPL providers through a single integration, with eligibility screening and checkout optimization on top.
-
Bank transfers
Local payments through domestic banking networks.
Bank transfers
Local bank transfers remain a preferred way to pay from SPEI in Mexico to PSE in Colombia and beyond across emerging markets.
Grow with bank transfersWe connect directly to local banking schemes and handle reconciliation, payment status, and settlement through a single integration.
-
Mobile money
Payments through digital wallets linked to mobile phone accounts.
Mobile money
Mobile money in Africa is closed-loop by design. M-Pesa users pay M-Pesa, MTN MoMo users pay MTN MoMo. Miss one network, and you miss every customer on it.
Grow with mobile moneyWe connect to the major mobile money networks across Sub-Saharan Africa, including M-Pesa, MTN MoMo, and Wave, so you're not managing five separate closed networks yourself.
-
Stablecoins
Blockchain-based payments with stable-value digital currencies.
Stablecoins
In markets with volatile currencies or FX friction, stablecoins are how dollar-exposed buyers want to pay. Cards distort this demand or lose it to spread.
Grow with stablecoinsWe provide a full stablecoin stack for acceptance, conversion, and settlement in eligible markets, orchestrated alongside local rails.
Growth in emerging markets runs beyond cards.
-
Latin America
41%
of eCommerce payments in Latin America are made entirely with local payment methods
-
Asia
70%
of eCommerce payments in Asia are made with eWallets
-
Africa
700M+
consumers in Africa without access to credit cards
Built for the way you get paid
-
Marketplaces
Customers span dozens of markets, each with the local payment methods they trust. One integration brings acceptance onto local rails, so customers pay in the method and currency they know.
-
Subscriptions & SaaS
Recurring payments fail more often in emerging markets, where local regulation can block foreign processors. Native recurring on local rails keeps subscriptions renewing where they would otherwise churn.
-
Gaming & digital goods
Part of your customer base won’t complete checkout without their local payment method. Local cards, wallets, instant payments, and buy now, pay later close that gap.
-
Travel
High-value bookings decline more often on cross-border acquiring, and every failed payment is a lost itinerary. Local acquiring raises approval rates on tickets, hotels, and packages, where drop-off costs the most.
Built within the markets where your business grows
-
Latin America
Latin America
Where cards share the checkout with Pix, Bre-B, OXXO, and local wallets, losing any of them means losing part of the market.
-
Argentina
-
-
Brasil
-
-
Chile
-
-
Colombia
-
-
Mexico
-
-
-
Asia
Asia
Where UPI, virtual accounts, and super-app wallets aren't alternatives to cards, but what most buyers use every day.
-
India
-
-
Philippines
-
-
Indonesia
-
-
Malaysia
-
-
-
Africa and the Middle East
Africa and the Middle East
Where mobile money moves more volume than cards in most Sub-Saharan markets, and BNPL helps converting buyers that online cards alone don't reach either.
-
Nigeria
-
-
South Africa
-
-
Egypt
-
-
Saudi Arabia
-
-
Kenya
-
-
 Argentina


 Chile


 Colombia


 India


 Indonesia


 Malaysia


 Nigeria


 South Africa


 Egypt


Why choose dLocal Payins
For your business
| dLocal Payins | Other providers | |
|---|---|---|
| Local licenses | dLocal Payins Already in place in each market | Cross-border processing Set up per country |
| Recurring payments | dLocal Payins Native on local rails | Cross-border processing Blocked in markets like India and Malaysia |
| Settlement currency | dLocal Payins USD, EUR, GBP, stablecoins, or local currencies | Cross-border processing Usually limited to foreign currencies |
| Reconciliation | dLocal Payins One dashboard, all markets | Cross-border processing Split across providers |
For your customers
| dLocal Payins | Other providers | |
|---|---|---|
| Payment methods shown | dLocal Payins Every local method that matters per market | Cross-border processing Limited local coverage, mostly cards and top wallets |
| Currency at checkout | dLocal Payins Local, familiar, expected | Cross-border processing Often foreign, adds friction |
| Approval rate on cards | dLocal Payins Local acquiring across every market you enter | Cross-border processing Foreign acquiring in most markets, more declines |
| Fraud checks | dLocal Payins Tuned to local behavior | Cross-border processing Global rules, one-size-fits-all |
Local at every step from checkout to settlement
-
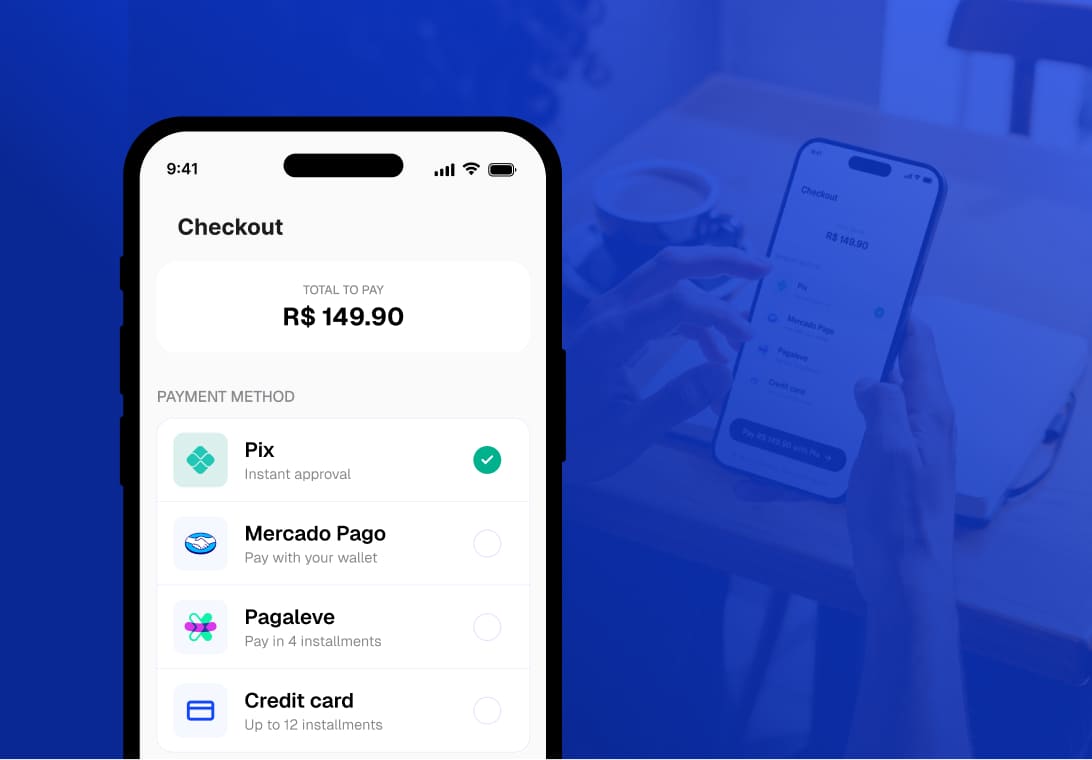
Checkout
Your checkout feels local and converts more
Your customers pay with the local payment methods they trust, from local cards and Pix in Brazil to UPI in India, always in local currency.
Local teams work with issuers, acquirers, and providers to find where customers drop off and fix it at the source.More customers finish checkout on the first try
-
Approval
More payments get through
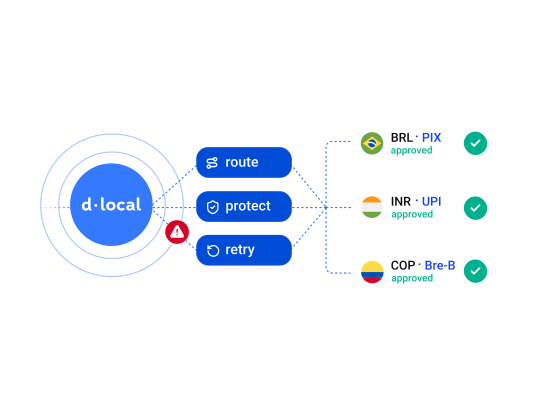
Smart Routing sends payments tothe acquirer most likely to approve it, and declines are retried within card network rules.
Tokenization keeps cards and selected local payment methods ready for repeat and recurring payments, with fraud checks tuned to local behavior.More approved revenue, with risk under control
Settlement
Your business gets paid globally
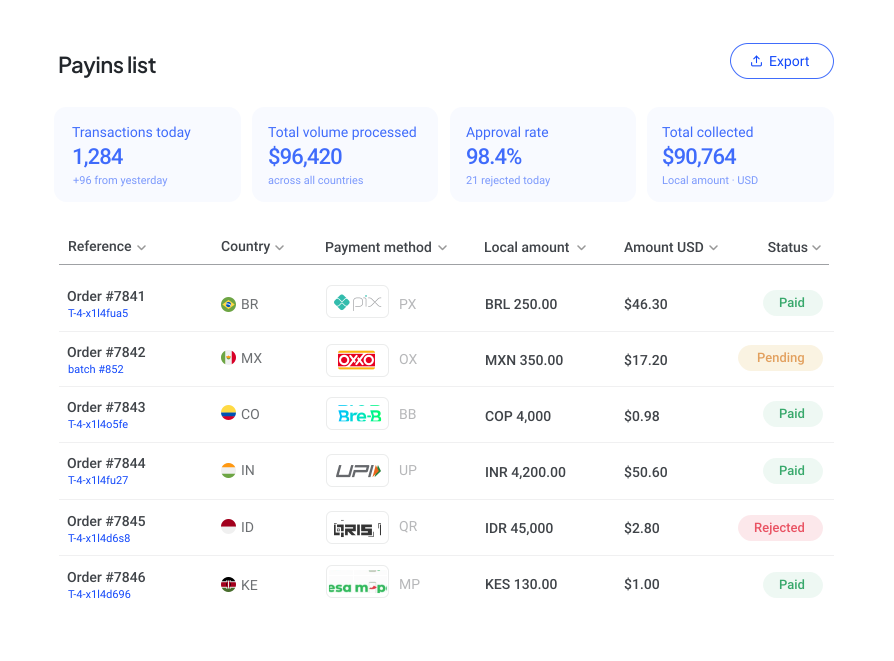
Receive funds in the currency and on the schedule you choose. Local FX, reconciliation, and compliance run behind the scenes, so every market feels like one.
Predictable cash flow across markets
Got questions?
-
Which countries and payment methods does dLocal Payins support?
dLocal Payins runs across 60+ emerging markets in Latin America, Africa & Middle East, and Asia. You get cards, real-time rails like Pix and UPI, wallets like GCash and Mercado Pago, mobile money, cash vouchers, and local BNPL, the exact mix per country.
-
How does dLocal Payins integrate with my existing payment stack?
You integrate once with dLocal by API or hosted checkout, then configure the markets and methods you want to enable. Most enterprise merchants run dLocal alongside their global acquirers, using dLocal specifically for emerging markets where local acquiring matters. Our reports and settlement plug into your BI or treasury tools.
-
How does dLocal Payins handle settlement and FX?
Your buyers pay in local currency using local methods. We collect funds locally, manage the FX conversion, and settle to your chosen currency (USD, EUR, GBP, supported stablecoins or selected local currencies) on the cycle you configure.
-
Do I need local entities or bank accounts in every country?
dLocal Payins operates through local entities, licenses, and FX access in each market, so you accept payments across 60+ emerging markets without setting up local infrastructure per country. If you need a full Merchant of Record solution, where dLocal owns the sale, tax, and compliance obligations end-to-end, that's what dMoRe delivers. Explore how dMoRe helps you expand faster here.
-
How long does it take to go live?
Timelines depend on your commercial model. A dedicated team walks through commercial alignment, technical integration by API or hosted checkout, sandbox testing, and staged market-by-market go-lives.
-
How does dLocal Payins pricing work?
Pricing is custom per merchant. It reflects your markets, payment mix, expected volumes, and settlement preferences. Talk to us for a quote.
 Your next growth stage
dLocal Payins helps you grow revenue across emerging markets
Accepting payments in a new market is one thing.
Converting there is another.